
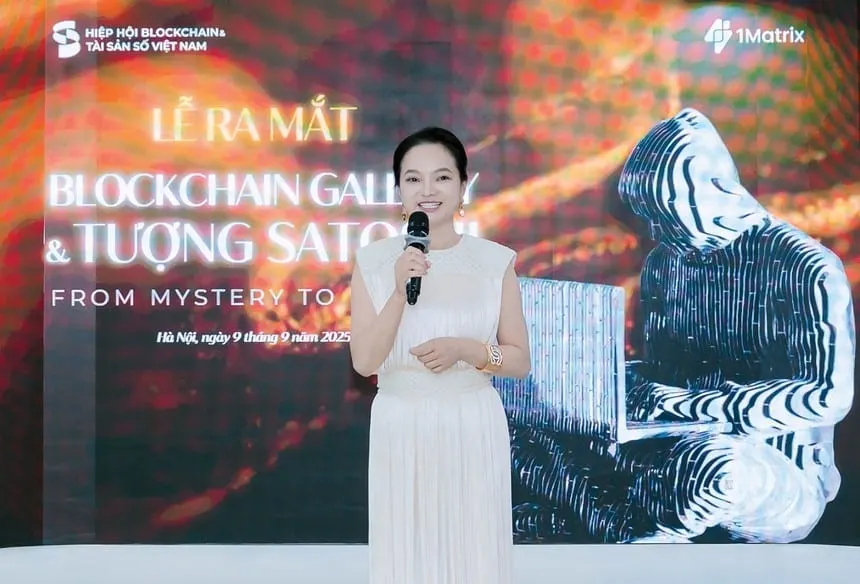
According to Ms. Nguyen Van Hien, Vice Chairwoman and General Secretary of the Vietnam Blockchain and Digital Assets Association (VBA), Vietnam is at a pivotal stage in the journey of digitizing assets. For the digital asset “Tet market” to become a modern, transparent and efficient capital market, the prerequisites are a consistent legal framework, sustainable liquidity and market trust.
If you compare the journey of digitizing assets to a trip from a “village Tet market” to a “modern capital market,” where would you say Vietnam is starting from today?
If digitizing assets is a journey, I believe Vietnam has left its “home ground” but is still at a pivotal stage, before fully stepping into a modern capital market in the true sense.
At this point, market demand has taken fairly clear shape. People, businesses and investors are growing familiar with the concepts of digital assets, digital transactions and digital capital flows. However, the implementing regulations and the standards for operating the market are still being completed. That is why this can be seen as the key stage for moving from a “village Tet market” - where transactions rely heavily on habit, personal trust and spontaneity - to an organized market structure with standards and oversight mechanisms.
The Law on Digital Technology Industry (Law No. 71/2025/QH15), effective from January 1, 2026, brings digital assets within the scope of regulation at the level of law for the first time, creating an important legal foundation for detailed regulations. At the same time, the Government's Resolution No. 05/2025/NQ-CP on piloting a crypto asset market (a type of digital asset) has set up a controlled testing mechanism, with requirements on information transparency, reporting obligations and a clear management roadmap for the transition period.
Internationally, crypto assets linked to real-world assets (RWA) have moved beyond isolated experiments to become an investment trend among financial institutions. According to Boston Consulting Group (BCG), a leading international consulting firm, the RWA market could reach about USD 19 trillion by 2030, equal to 10% of global GDP. In this current, Vietnam needs to complete its institutional framework quickly enough and rigorously enough to manage risk without missing the opportunity.
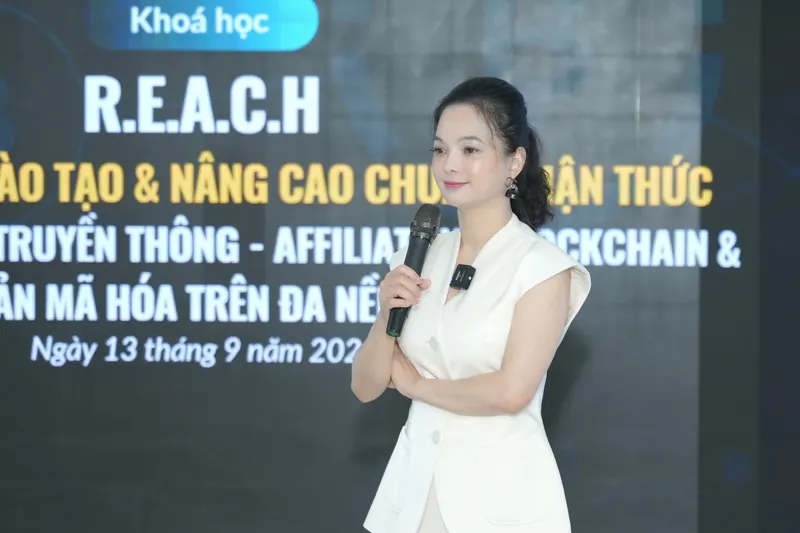
Ms. Nguyen Van Hien, Vice Chairwoman and General Secretary of the Vietnam Blockchain and Digital Assets Association.
At a Tet market, buyers and sellers trust each other through reputation and acquaintance. When assets are digitized and traded on blockchain, through what mechanisms is “trust” established?
At a village Tet market, trust between buyer and seller is built on familiarity and reputation accumulated over time. In a digital environment, however, trust cannot rest on feeling; it must be “designed” into specific mechanisms and frameworks.
The first is the legal framework and property rights. Tokenizing an asset is not simply “putting the asset on blockchain”; it is a process of standardizing the rights attached to that asset: who the owner is, who has the right to issue, who is responsible for custody, and how legal obligations are established. Only when rights and responsibilities are clearly defined can digital assets in general, and crypto assets in particular, take part in the market sustainably.
The second is identification and compliance. KYC and AML/CFT requirements are not barriers but foundational conditions for the market to operate safely. These standards must not only satisfy the domestic legal framework but also be compatible with global standards, especially the recommendations of the Financial Action Task Force (FATF). For example, the Travel Rule helps limit the risk of money laundering and terrorist financing, strengthening trust in the entire system.
The third is information transparency and market discipline. Information disclosure, independent audit and risk reporting need to become mandatory standards. The International Organization of Securities Commissions (IOSCO) has repeatedly stressed that investor protection and reducing information asymmetry are pillars of a sustainable digital asset market.
Finally, there is technology security and systemic risk management. For RWA models, connecting on-chain data with off-chain assets requires supporting mechanisms such as oracles, custody, ownership registration and independent audit. The Bank for International Settlements (BIS) views tokenization and the unified ledger model as the future of financial infrastructure, helping reduce fragmentation and improve market operating efficiency.
From the Association's perspective, which types of assets can be digitized early, and which “goods” need more time?
Under Resolution No. 05/2025/NQ-CP, the crypto assets piloted include two groups: crypto assets not linked to real-world assets, and crypto assets linked to real-world assets. The market is especially awaiting the second group, which excludes securities and fiat currency. However, which real-world assets to prioritize for tokenization still awaits specific guidance from regulators.
From a professional standpoint, I believe priority should go to tokenizing assets with a high degree of standardization, clear property rights and a relatively transparent valuation mechanism, such as government bonds and corporate bonds. For assets that lack complete legal and valuation data, tokenizing too early could increase disputes rather than deliver the transparency expected.
For highly transparent assets, we should leverage the advantages of crypto assets: 24/7 trading and low costs, especially for small transactions. This is the key to boosting secondary-market liquidity. Only when a secondary market for crypto assets is formed and operating effectively will the strengths of blockchain technology truly come into play.
How can blockchain and digital assets become more familiar to individual investors, the way people have grown used to cashless shopping at the market?
People do not need to understand how blockchain works, just as they do not need to understand the NAPAS infrastructure to use cashless payments. Nor do they need to know what a QR code is; they only need to know how to scan one safely on a smartphone. That is when advanced technology has truly become part of daily life.
What users care about first is the benefit: faster, more convenient, more transparent and safer.
Trust in digital assets needs to be built in sequence, from standardization to mass adoption. Investors only truly engage when they see transparent cash flows, reasonable transaction costs and clearly protected rights. Alongside this comes risk education, giving investors the ability to protect themselves against increasingly sophisticated threats.
It must also be stressed that user experience plays a key role. When processes are simple, responsibilities are clearly assigned and protection mechanisms are effective, market acceptance will rise very quickly.
In the journey of digitizing assets, the legal framework can be compared to the “market management board.” What do you expect from upcoming policy steps to make the market more transparent and orderly?
The legal framework is the “market management board,” responsible for setting standards, assigning responsibilities and building mechanisms to prevent and handle risks for the market. The period from 2026 onward is especially important, as the key legal foundations have taken shape and are beginning to be enforced.
With the National Assembly's passage of Resolution No. 222/2025/QH15 of June 27, 2025 on establishing International Financial Centers in Da Nang and Ho Chi Minh City, as well as the special mechanisms and policies to promote innovation under Resolution No. 136/2024/QH15 for Da Nang and Resolution No. 98/2023/QH15 for Ho Chi Minh City, the institutional framework for the digital asset market and a modern capital market in Vietnam is gradually taking shape toward being transparent, controlled and close to international practice.
I expect the risk-based management approach and the controlled pilot mechanism to be maintained, along with stronger inter-agency coordination, because digital assets are not only a matter of technology or finance but also involve banking, securities, taxation, cybersecurity and consumer protection.
When “bringing goods to the digital market,” what do you think is keeping trading from becoming truly active: liquidity, valuation, or the connection between sellers and buyers?
Liquidity, valuation and the connection between supply and demand are indeed key factors of any market. Looking deeper from an institutional angle, however, the “digital market” is not yet crowded not because buyers or sellers are lacking, but because the “rules of the game” at the foundational level are still being completed.
For a market to be lively, it takes more than a decision to open it; it also takes specific rules on how to display goods, trade, pay and handle risks. The same applies to the digital asset market. After the National Assembly issues the laws and resolutions that form the foundation, the next role belongs to subordinate legislation. The Government needs to issue guiding decrees and resolutions; ministries and agencies need to make operational procedures, technical standards and compliance obligations concrete; and at the local level, decisions of the People's Committees will enable implementation suited to each area's specific conditions.
Until these policies are connected consistently, the market will struggle to form all of its components, such as a secondary market, custody and clearing mechanisms or market makers, which directly affects its ability to generate liquidity. In that situation, even digitized assets can easily end up thinly traded or priced mainly on short-term sentiment rather than real economic value.
For the market to develop sustainably, asset tokenization must be placed within a complete ecosystem, tied to independent audit, credit ratings and clear accounting standards. Once the legal framework at both the central and local levels is complete, institutional investors and long-term capital will participate more, giving the market greater depth and stability and reducing its dependence on short-term speculative waves.
On the occasion of the Binh Ngo (Year of the Horse) Tet, if you were to send a “New Year wish” for Vietnam's journey of digitizing assets, what further “springs” do you hope our modern capital market will welcome in the next few years?
Looking down the road ahead, I believe Vietnam's journey of digitizing assets is entering the early stage of a spring full of promise.
First is the spring of standards, when Vietnam forms a clear system of standards and regulations for digital assets and tokenization models, in line with international practice. Once this framework is transparent and stable enough, businesses will have a basis to invest for the long term, and investors can enter the market with greater peace of mind.
Second is the spring of real-world application. Digitizing assets should move into fields that create clear economic value, such as the capital market, green finance or supply chains, rather than stopping at scattered pilot models or short-term speculative products. When technology is tied to real needs and real cash flows, the market will generate its own sustainable momentum.
Last is the spring of trust, when risks are identified and managed effectively. When investors and users clearly feel that their rights are protected by specific standards and mechanisms, the market will be able to expand in both quality and quantity.
Every Tet is a time to look back and prepare for a new cycle. For the asset digitization market, the most important preparation in the coming period lies not in the speed of expansion but in standardizing data, perfecting the institutional framework, strengthening supervisory capacity and developing human resources. When these foundations are firmly in place, the journey from the “village Tet market” to the “modern capital market” will no longer be a figure of speech but a process measurable in trust, liquidity and the quality of capital flows.