
Tax policy for digital assets must be designed with care, balancing the interests of the State, enterprises and investors while keeping Vietnam competitive in attracting international capital.
In an interview with Economy & Finance Magazine, Mr. Phan Duc Trung, Chairman of the Vietnam Blockchain and Digital Assets Association (VBA) and Chairman of VMatrix, shared his views on the legal foundation for the digital asset market, from trading and taxation to risk management and long-term development.
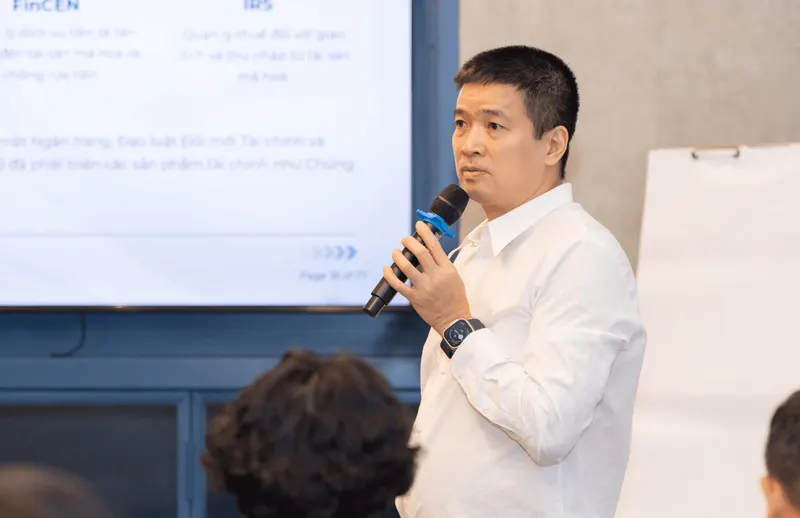
Mr. Phan Duc Trung, Chairman of the Vietnam Blockchain and Digital Assets Association (VBA) and Chairman of VMatrix.
In his speech at the opening session of the 14th Party Congress, General Secretary To Lam stressed the need to "complete the institutional framework, taking implementation as the measure." How would you describe the recognition of crypto assets as property under the Civil Code as a concrete step toward that principle?
- From January 1, 2026, all crypto assets are officially recognized as property under the Civil Code. Once established as property, related transactions can be fully governed by the Civil Code, without distinguishing any security element. Crypto assets can therefore be treated as an ordinary type of property, making transfers, inheritance and dispute resolution easier and clearer.
Recognizing crypto assets as property under the Civil Code reflects the spirit of facing practical reality squarely, respecting objective laws and bringing new economic relationships within the legal framework. It helps the State move from a precautionary approach to management based on the rule of law, laying the foundation for transparent, consistent and accountable policy enforcement, in line with the spirit set out by the 14th Party Congress.
The report of the 13th Party Central Committee on the documents submitted to the 14th Party Congress, delivered on the morning of January 20, stressed "creating a favorable business environment and ensuring property rights and the freedom to do business." With legal status now established, how should tax and fee policy for crypto assets be implemented to secure State revenue without reducing the market's appeal to domestic and foreign investors?
- Under the amended Personal Income Tax Law passed by the National Assembly on December 10, 2025, income from the transfer of digital assets is now subject to personal income tax at a rate of 0.1%. The Personal Income Tax Law takes effect on July 1, 2026.
This rate is equivalent to the tax applied to securities transactions. However, detailed implementation should wait until the market is operating steadily and the transacting parties are clearly defined. Tax policy in this field should be designed to balance the interests of the State, enterprises and investors.
As Vietnam seeks to attract capital and professional foreign investors to operate in the country, tax policy is not only about how much to collect, but also about creating a competitive, transparent and reasonable environment. This area therefore needs continued study and refinement, especially as digital asset exchanges are formed and begin to operate in the coming period.
When the digital asset market officially goes live, how do you expect liquidity and market size to change compared with the pilot phase or the earlier spontaneous activity?
- Under the relevant resolution, up to five entities may be licensed. From what I understand, the State Securities Commission has been proactive in drawing up the necessary regulations and is ready for the licensing process. How many entities are actually licensed, however, will depend on their applications, how well they meet the conditions, and the appraisal and approval results of the regulator. Even if the number stops at five exchanges, many more entities will certainly want to take part.
The question is how this market will take shape and grow in the coming period. Once the market officially goes live, liquidity and market value will change considerably compared with the pilot phase or the earlier spontaneous activity, but the extent of that impact should be viewed with caution. International experience shows that in the early stage, new asset markets are usually much smaller than traditional stock markets. The main reasons are strict compliance requirements and tight oversight to safeguard the system, especially anti-money laundering rules.
Only as the institutional framework matures and a balance is struck between risk management and market development will these markets have room to grow. In practice, even globally, the digital asset market is still considerably smaller than traditional financial markets. It is nonetheless expected to become a new asset class that opens an additional channel for raising and accessing capital, not limited to listed companies.
Although its initial scale is modest, this market is tied to a long-term development trend. By some forecasts, by 2033 transactions involving digital assets could account for about 10% of total global transaction value, an enormous scale. More importantly, innovation in technology and trading models from the digital asset market is expected to create positive reform pressure, pushing traditional financial markets to raise their standards and gradually move closer to international practices and norms.
After January 15, when the Prime Minister directed digital asset exchanges to be ready for official operation, what recommendations or cautions do you have for investors entering this market?
- The Prime Minister's direction to accelerate implementation, with the Resolution on the pilot licensing of crypto asset exchanges already issued, shows a clear determination to build a new investment channel. The market has generally welcomed this signal with high expectations, but there are important points investors need to pay close attention to.
First, consider the structure of Vietnam's financial market. Individual investors consistently account for a very high share of Vietnam's stock market, about 85%, while institutional investors remain relatively few. This is almost the opposite of international practice, where developed markets are dominated by institutional capital. It makes trading very active, but it also demands a great deal of knowledge, experience and risk management ability from individual investors.
Crypto assets are generally riskier than traditional securities. In a personal portfolio allocation strategy, they should therefore be placed in the high-risk category, with a reasonable and limited weighting, rather than treated as a primary investment channel.
Second, during the initial pilot phase, liquidity in Vietnam's crypto asset market is unlikely to be as active as the stock market, where trading value reaches billions of US dollars a day. This is common in international experience, and investors should hold appropriate expectations.
Third, many crypto assets, by nature, are not tied to a balance sheet or financial statements as stocks or bonds are. Some types of digital assets, including native tokens or core assets, are valued mainly on technology, operating model and market expectations. Investors must therefore equip themselves with thorough knowledge, because their value cannot be assessed with traditional financial indicators.
In addition, the digital asset market also differs greatly from the stock market in its operating model. The stock market has a centralized exchange organized and managed uniformly by the State, whereas digital asset exchanges operate autonomously, with the State supervising through regulators, including the State Securities Commission. The assets listed on an exchange are proposed by the exchange itself, which is responsible for them. Risk management therefore becomes all the more important for investors.
High risk usually comes with expectations of high returns, but investors must be clearly aware of their responsibility to make their own assessments and bear their own risks, and to comply fully with regulations on trading, taxes, fees and penalties.