
Publicly disclosing proof of reserves on-chain and tightening security are vital to avoiding systemic risk and protecting investors during the crypto asset exchange pilot.
Vietnam is entering the stage of reviewing applications before granting pilot licenses to crypto asset exchanges under Resolution No. 05/2025/NQ-CP. Against this backdrop, a Dan Tri reporter spoke with Mr. Nghiem Minh Hoang, Senior Strategy Expert at VMatrix, about the legal, technical and investor protection issues the market is watching.
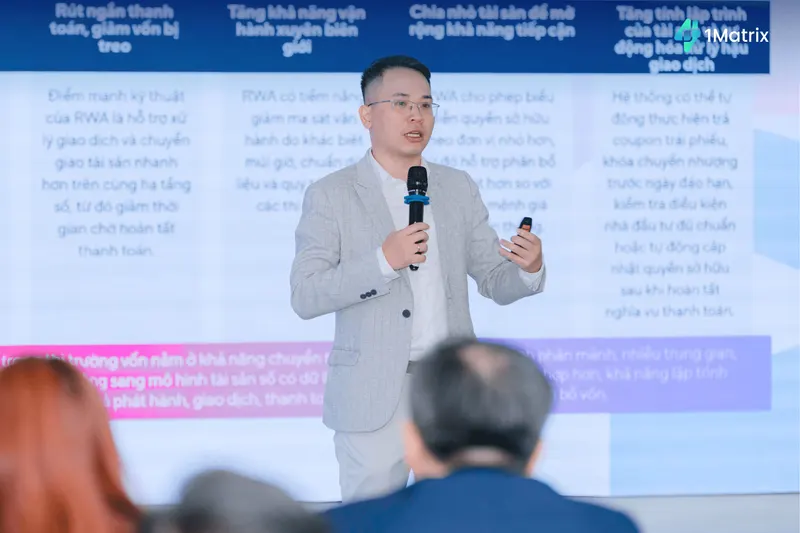
Mr. Nghiem Minh Hoang, Senior Strategy Expert, VMatrix.
A cautious step toward shaping a mainstream crypto asset market
Under Resolution No. 05/2025/NQ-CP, with its five-year pilot period, how do you assess the "openness" and the "strictness" of this roadmap, as we are in the stage of reviewing applications before granting pilot licenses to crypto asset exchanges in Vietnam?
- Resolution 05 is shaped by a philosophy of "conditional openness," a cautious, controlled approach that suits a country still completing the legal framework for a relatively new asset class. The "openness" lies in the fact that, for the first time, Vietnam has a sandbox mechanism (a controlled pilot) for the crypto asset market, running for five years and allowing continuous operation even after the pilot period ends, until a replacement regulation is issued.
That means the market is not suddenly "switched off" when the sandbox ends. The licensing process also has clear time limits: after receiving a complete and valid dossier, the Ministry of Finance has 30 days, in coordination with the Ministry of Public Security and the State Bank of Vietnam, to review it and issue a decision.
The "strictness" shows in the conditions for market entry. A minimum charter capital of VND 10 trillion is the threshold set to ensure participants' financial capacity. The information technology system must reach Level 4 of information system security before operating. The number of participating organizations is capped at five during the pilot phase. The State retains the right to suspend, halt or terminate the pilot when risks arise that affect financial and monetary security or social order.
Overall, the design of Resolution 05 puts the stability of the financial system ahead of the speed of market development, a well-founded choice given the lessons from incidents in the global crypto asset market in recent years.
From your perspective, as Vietnam becomes the 46th country to legalize crypto assets, which lessons from international experience deserve particular attention?
- According to Atlantic Council data, of the 75 countries it tracks, 28 have built a framework covering all four pillars: taxation, AML/CFT (anti-money laundering and countering the financing of terrorism), consumer protection and licensing. This figure reflects a common reality: legalization is the first step of a longer journey, building a supervisory system that is comprehensive and substantive.
The collapse of the FTX exchange in 2022 is often cited as an important reference point, and the lesson from this event does not lie in technology.
Later analysis pointed to more fundamental problems: conflicts of interest when one organization performs multiple functions within the same ecosystem, failure to separate customer assets from the company's own assets, and a lack of transparency about the state of assets and liabilities. IOSCO's 2023 policy recommendations also identified three central risks to be controlled: conflicts of interest, protection of customer assets, and fraud and market manipulation.
International experience also offers a standard that Vietnam should integrate proactively from the start. In its 2025 update, the Financial Action Task Force (FATF) reported that 73% of jurisdictions in the group that do not prohibit virtual asset service providers (VASPs) have enacted legislation implementing the Travel Rule, a mechanism requiring VASPs to transmit identifying information on the originator and the beneficiary with each transaction.
This is an important layer of defense that many advanced markets have built, and Vietnam has a full legal basis to implement it from the pilot stage, since Resolution 05 already requires exchanges to apply AML/CFT measures equivalent to those of financial institutions.
If we integrate the Travel Rule into the supervisory framework early, Vietnam will not only avoid the gaps that collapsed exchanges paid for, but also position itself as a trustworthy market in the eyes of international partners, a clear competitive advantage when attracting capital and cross-border cooperation.
What is your assessment of the 0.1% per-transaction tax under the newly issued Circular 32/2026, in terms of investor sentiment and the development of domestic exchanges?
- Circular No. 32/2026/TT-BTC takes effect from March 27 and applies throughout the pilot period. Structurally, the transfer and trading of crypto assets are not subject to VAT; individuals pay personal income tax of 0.1% on the value of each transfer made through a licensed service provider; and foreign organizations trading through exchanges pay corporate income tax of 0.1% on the revenue of each transaction.
Overall, this is a relatively simple tax model that is convenient for collection and withholding at source, an important factor while the market is still taking shape. This structure creates an incentive to bring trading onto licensed platforms, which helps make asset flows more transparent. At the same time, a fixed tax rate on each transaction lets investors determine their costs up front and limits unexpected expenses.
However, one point to keep monitoring is that taxing the revenue of each transaction, rather than net profit, may raise costs for high-frequency traders. This is not a structural limitation of the policy but a characteristic to be assessed during actual operation, so that regulators have a basis to adjust appropriately when needed.
To keep users' assets safe, beyond infrastructure standards, how should exchanges coordinate with the Ministry of Public Security and the State Bank of Vietnam in monitoring suspicious transactions?
- Under the design of Resolution 05, coordination is organized in three tiers. The first is periodic reporting: by the 10th of each month at the latest, service providers must inform the Ministry of Finance, the State Bank of Vietnam and the Ministry of Public Security of the state of the trading market.
The second tier is long-term data storage on servers located in Vietnam for at least 10 years, including transaction history, wallet addresses, IP address history, access device information and linked bank accounts. This is a data repository for later digital investigations.
The third tier, the most important from a crime prevention standpoint, is the AML/CFT framework. The 2022 Law on Anti-Money Laundering and Circular No. 27/2025/TT-NHNN require reporting entities to report suspicious transactions to the Anti-Money Laundering Department regardless of transaction value, and even if the transaction has not been completed. Resolution 05 goes further by requiring crypto asset service providers to apply AML/CFT measures equivalent to those of financial institutions.
One area to keep developing in the coming period is a mechanism for sharing alerts in real time among exchanges, the State Bank of Vietnam, the Ministry of Public Security and other relevant regulators. The crypto asset market runs 24/7 and risk can move very fast, so the ability to respond early is an important complement to the periodic reports already in place.
As cybercrime grows more sophisticated, which security technologies should be mandatory for entities seeking pilot licenses?
- Looking at international practice, especially the operating experience of large crypto asset exchanges such as Coinbase in the United States, which is both a trading platform and a custodian of assets for institutional investors, we can see that security today no longer rests on individual technologies. It lies in how the entire custody model is designed as an end-to-end "control chain."
In the past, security was generally understood as measures against technical attacks, and custody was tied to key management and the distinction between hot and cold wallets. In practice, however, modern risk comes less from breaking security algorithms and has shifted toward attacks on digital identity management, user behavior, internal errors or weaknesses in the service supply chain.
A secure system is therefore defined not by the number of technologies it uses, but by its ability to design a control chain tight enough that no single weak point can lead to a loss of assets. This chain has many layers: from identity verification, access control and separation of internal authority to multi-layer approval mechanisms and continuous transaction monitoring.
Under Resolution 05, exchanges must meet Level 4 information security standards, already the highest level of cybersecurity standards. However, to operate effectively, these standards must sit within an overall custody architecture, where technology, processes and people are controlled together.
In other words, the question is no longer "which technology should be applied," but "how to design the control chain" so that an error at any point, from users and internal staff to external partners, cannot reach the core of the assets.
Prioritize transparency to protect investors' rights
One of the issues investors care about most today is liquidity and the safety of deposited assets. What do you think of the proposal that exchanges be responsible for transparently and regularly disclosing their reserves, so that users can check directly on-chain?
- Transparency on reserve assets is in fact a lesson drawn from several major incidents in the global market, including FTX. What those incidents had in common was not a technical failure but that users and regulators had no tools to independently verify the actual state of reserve assets against the exchange's liabilities.
In that context, the approach in Resolution 05 shows a clear direction on transparency. The requirements to separate customer assets from the company's assets, together with obligations to disclose information periodically and on an ad hoc basis, show a clear commitment to investor protection. Notably, for unusual events such as technology incidents affecting trading, the disclosure deadline is set at 24 hours, which strengthens the accountability of service providers.
Proof of reserves (POR), a mechanism that lets users verify on-chain for themselves that the exchange holds enough assets to match their account balances, can be seen as an additional step worth considering in the roadmap for completing the governance framework. When fully designed, including confirmation from an independent audit and simultaneous disclosure of liabilities, this mechanism can form a layer of transparency that can be verified directly, thereby strengthening market confidence.
Should proof of reserves be mandated as a technical standard, or only recommended so that exchanges adopt it voluntarily to build credibility?
- This is a matter of policy design, where the approach depends on the priorities at each stage of market development. In practice, both approaches, voluntary and mandatory, have a basis and are not mutually exclusive.
From a market perspective, voluntary POR serves as a signal of transparency. Proactively disclosing reserves helps exchanges build credibility, create a competitive advantage and attract investors who demand verification of assets. During the pilot phase, while the number of licensed organizations is limited, competition based on transparency can work effectively.
However, a voluntary mechanism does not guarantee uniformity. Making POR a mandatory standard, by contrast, can set a minimum benchmark that applies across the market. The core issue in designing this standard is not only disclosing assets, but also disclosing liabilities and providing for independent verification. Without these components, the disclosed information would reflect only part of an organization's actual financial position.
From international experience, a commonly referenced path is to proceed step by step. In the first stage, keep mandatory requirements at a basic level, such as the separation of assets and periodic disclosure under Resolution 05, while encouraging on-chain POR as a transparency practice.
Once the market has accumulated enough operating data and technical capability has been verified, there will be a firmer practical basis for upgrading this standard to a mandatory obligation, with requirements for independent verification and disclosure of liabilities.
If a technical incident occurs or an exchange becomes insolvent during the pilot phase, what specific provisions does the current legal framework have to protect users' civil rights and the inheritance rights to digital assets?
- The current legal framework has established some substantive user protection mechanisms, while some areas are still being specified further.
On incident handling and license revocation, Resolution 05 stipulates that a service provider must disclose unusual information within 24 hours when a technology incident affects trading. If a license is revoked, the provider has 45 days to settle all customer assets and transfer them to an organization chosen by the customer or designated by the Ministry of Finance to receive them. This is a controlled "exit" mechanism that ensures users are not cut off from their assets if an exchange stops operating.
At the level of law, the Law on Digital Technology Industry, in force since the beginning of the year, establishes digital assets as property under the 2015 Civil Code. That opens the way, legally, for ownership rights, inheritance rights and other civil rights over digital assets.
However, in its analysis of the Law on Digital Technology Industry, the Ministry of Justice also noted gaps in defining ownership and control rights and in implementing guidance. On the specific question of inheriting digital assets held in custody at an exchange when the account holder dies, there are as yet no publicly available provisions detailed enough on the handling procedure. This is a highly practical matter that can be specified progressively during the pilot.
How will the emergence of mainstream exchanges affect "underground exchanges" and the decentralized transactions that currently carry many fraud risks in Vietnam?
- Resolution 05 establishes an important legal tool for defining market boundaries. Under Resolution 05, six months after the first crypto asset service provider is licensed, domestic investors who trade outside organizations licensed by the Ministry of Finance may face administrative penalties or criminal liability, depending on the nature and severity of the violation. This provision draws a clear legal line between the licensed sector and activity outside the system.
On market impact, once mainstream exchanges begin operating with a clear legal basis, organized liquidity and a transparent tax mechanism, some investors may shift to licensed platforms, especially those who prefer to operate within the legal framework.
This shift would not only help restructure capital flows but also create trading data that falls within the supervised area, which better supports efforts against financial crime.
With a market of about 17 million Vietnamese people holding crypto assets, equal to nearly 17% of the population, and capital flows of up to USD 220 billion, licensing official exchanges will help reduce fraud risks linked to crypto assets, strengthen anti-money laundering and counter-terrorist financing capabilities, and contribute in practical ways to the sustainable development of Vietnam's digital financial market.